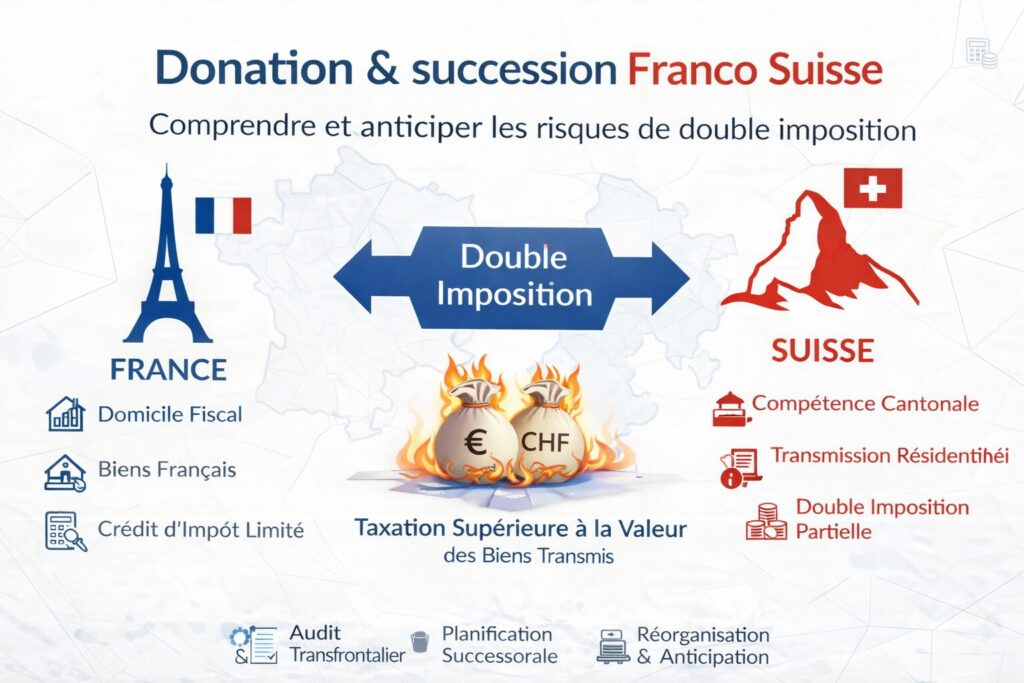
Wealth transfers involving France and Switzerland constitute a sensitive area. In the absence of a bilateral convention on gifts and inheritance, certain situations may lead to extremely high levels of taxation, sometimes exceeding the actual value of the assets transferred.
Drawing from the practical experience of Avacore Wealth Planning, which specializes in cross-border matters, this article provides a structured analysis of the applicable rules, double taxation mechanisms, and wealth planning solutions to be implemented before any transfer.
Absence of a Franco-Swiss Tax Treaty on Gifts and Inheritance
For many years, France and Switzerland were bound by a tax treaty applicable to inheritance, but not to gifts. This treaty was unilaterally terminated by France, resulting in the disappearance of any specific conventional framework between the two States.
The consequence is direct and significant: each country now freely applies its domestic law regarding gift and inheritance tax, without limitation or systematic coordination. This situation mechanically increases the number of cases taxable in France and creates unresolved areas of double taxation.
Residence and Tax Domicile: A Fundamental Distinction
Swiss Resident but Tax Domiciled in France
A common confusion consists of equating tax residence for income tax purposes with tax domicile applicable to gift and inheritance tax. However, these concepts follow distinct logics.
It is entirely possible to be a Swiss resident under income tax treaties, while being considered tax domiciled in France for gratuitous transfers, provided the criteria of French domestic law are met.
French Tax Domicile Criteria
The tax domicile criteria for gifts and inheritance are alternative. A single criterion is sufficient to establish a connection to France.
- The home, defined as the place of residence of the spouse and minor children.
- The principal place of stay, corresponding to the country in which the person stays most, without reference to a minimum duration.
- The principal professional activity carried out in France.
- The center of economic interests, a key notion often misunderstood, corresponding to the main source of income.
This last criterion is particularly tricky. Rental income, dividends, capital gains, and retirement pensions paid by French organizations are all elements likely to lead to a French tax domicile, even in the absence of physical presence in the territory.
Tax Consequences when Tax Domicile is in France
When the deceased or the donor is considered tax domiciled in France, the rule is particularly strict. The entire transferred estate is subject to French gift or inheritance taxes, without distinction:
- between movable and immovable property
- between assets located in France or Switzerland
- regardless of the domicile of the heirs or donees
This rule requires extreme vigilance upstream to avoid a reclassification often discovered late, at the time of transfer.
Role of the Tax Domicile of Heirs and Donees
When the deceased or the donor is not tax domiciled in France, the analysis shifts to the situation of the heirs or donees.
If a beneficiary has been tax domiciled in France for a significant period during the years preceding the transfer, the entirety of their share becomes taxable in France, even when the assets are located in Switzerland.
An essential point must be emphasized: the situation of one heir is independent of that of the others. A single beneficiary domiciled in France will bear French taxation on their share, without affecting the other heirs.
Taxation Limited to French Assets: The Residual Scenario
When neither the deceased nor the heirs meet the French tax domicile criteria, or when the duration of connection is insufficient, France limits its right to tax to French assets.
French assets notably include:
- real estate located in France
- shares of French civil real estate companies
- shares of French companies, listed or unlisted
- financial assets of French origin, even if held abroad
Swiss Taxation of Gifts and Inheritance: Cantonal Competence
In Switzerland, gift and inheritance taxes fall exclusively under the competence of the cantons. There is therefore no harmonized federal regime, which implies a systematic cantonal analysis.
In summary:
- if the deceased or the donor is domiciled in a canton, that canton generally taxes all assets, with the exception of real estate held directly abroad
- if the deceased is not domiciled in Switzerland, the cantons tax real estate located in their territory and, depending on the case, certain movable assets
This cantonal diversity constitutes fertile ground for the emergence of double taxation.
Identifying the Main Double Taxation Scenarios
Conflict of Tax Domicile
Each state considers the deceased or the donor to be domiciled in its territory and applies worldwide taxation.
Swiss Domicile and Heir Domiciled in France
France taxes all transferred assets, while the Swiss canton of domicile also taxes the estate, with the exception of French real estate held directly. Double taxation then applies to the majority of assets.
French Domicile with Assets in Switzerland
France taxes the entire estate, while certain Swiss cantons tax assets located in their territory. Double taxation primarily concerns Swiss assets.
Swiss Domicile with Limited Taxation in France
In this configuration, France taxes French assets, while the canton of domicile taxes movable assets, generating double taxation on certain French financial assets.
Double Taxation Relief Mechanisms
Swiss Side: Variable Solutions Depending on the Cantons
Not all cantons provide for a mechanism to eliminate double taxation. Some, like Geneva, offer no possibility of neutralization.
Other cantons allow the deduction of taxes paid abroad from the liabilities of the estate. This method reduces the taxable base but does not completely eliminate double taxation, which remains partial.
French Side: Limited Tax Credit
France grants a tax credit for taxes paid abroad, but only for non-French assets. French assets remain excluded from this mechanism, which leaves unresolved areas of double taxation.
Les situations les plus à risque
The most problematic cases concern:
- shares of French companies
- financial assets deposited in France
- shares of French real estate companies
- transfers to non-relatives
In certain cantonal configurations, the complete absence of a corrective mechanism may lead to cumulative taxation exceeding the value of the transferred assets, placing heirs in the economic impossibility of accepting the inheritance.
Best Practices for Anticipating and Securing Transfers
- Conduct a cross-border wealth audit before any gift or anticipated inheritance.
- Precisely identify the nature and location of assets, particularly French movable property.
- Reorganize the ownership of certain assets, especially financial or movable ones, when risk is identified.
- Anticipate transfers through mechanisms compatible with French and Swiss law.
- Export or sell certain sensitive assets when necessary.
Conclusion : anticiper pour éviter l’irréversible
The taxation of Franco-Swiss gifts and inheritance perfectly illustrates the need for a proactive wealth planning. In the absence of conventional coordination, certain situations can become irreversible after death, leaving heirs without a solution.
In a France-Switzerland inheritance, the key lies in a global approach integrating civil law, international taxation and cantonal analysis, conducted sufficiently early. Once the transfer is open, it is often too late to correct the effects of excessive double taxation.
For cross-border estates, support from a family office, a tax lawyer or a notary mastering both French and Swiss systems is a decisive factor for security and peace of mind.